 Money Smart Guides
Getting out of debt can feel impossible when you’re in the middle of it.
I know because I’ve been there.
At my worst, I had more than $10,000 in credit card debt and no real plan for paying it off.
I remember dreading the mail because I didn’t want to see another bill.
I avoided checking my bank account because I was afraid of what I’d find.
And every month, I wondered how I was going to make my credit card payments and still have enough money left to live.
Eventually, I realized avoiding my debt wasn’t making it disappear.
It was only making the problem, and the stress that came with it, worse.
So I finally faced it.
I figured out why I kept overspending, created a realistic debt payoff plan, increased my income, and started putting extra money toward my balances.
I made mistakes along the way, including trying to pay off my debt so aggressively that I eventually burned myself out and started spending again.
But I adjusted my plan, kept going, and paid off more than $10,000 in credit card debt in a little over a year.
In this guide, I’ll show you how to get out of debt step by step, including how to choose which debt to pay first, lower your interest costs, find extra money for your payments, and stay motivated until your balances finally reach $0.
I’ll also show you what worked for me, what didn’t, and the mistakes I’d avoid if I had to do it all over again.
You don’t need a perfect plan to start getting out of debt. You just need a plan you can actually stick with.
Quick Answer: How to Get Out of Debt
The best way to get out of debt is to create a repayment plan that allows you to consistently pay more than the minimum without making your budget so restrictive that you can’t stick with it.
Start by listing every debt you owe, including the balance, interest rate, and minimum payment. Then follow these steps:
- Stop adding to your debt. Avoid new credit card balances and unnecessary borrowing while you’re working on your payoff plan.
- Create a realistic budget. Know how much money is coming in, where it’s going, and how much you can consistently put toward debt each month.
- Build a small emergency fund. Having some cash available for unexpected expenses can keep a car repair or medical bill from going right back onto a credit card.
- Choose a debt payoff strategy. The debt snowball focuses on your smallest balance first, while the debt avalanche targets the debt with the highest interest rate.
- Pay more than the minimum. Continue making the minimum payment on every debt, then put as much extra money as you reasonably can toward the debt you’re targeting.
- Look for ways to lower your interest costs. Depending on your situation, this could include negotiating a lower rate, using a balance transfer, or consolidating high-interest debt.
- Find extra money for your debt. Cut expenses that don’t matter to you, sell things you no longer need, or temporarily increase your income and put that money toward your balances.
- Track your progress. Watching your balances fall gives you small wins along the way and makes it easier to stay motivated.
The important part is consistency, not perfection.
I learned this the hard way when I tried putting nearly every available dollar toward my debt.
The plan was so restrictive that I began resenting it and started spending again.
Once I gave myself a little room to enjoy life while continuing to make extra payments, I finally had a debt payoff plan I could stick with.
We’ll break down each of these steps below so you can create a plan that works with your income, expenses, and amount of debt.
My Debt Story: How I Ended Up With More Than $10,000 in Credit Card Debt
Before I explain exactly how to get out of debt, I want to show you how I got there in the first place.
Not because my story is unusual. Actually, it’s probably the opposite.
I didn’t wake up one morning $10,000 in debt. It happened slowly, one decision at a time.
It Started With Just $2,000
My credit card mistakes started during my sophomore year of college.
Before then, I was pretty responsible with credit cards. I used them and paid the balance off every month.
Then I met a girl.
Suddenly I was going out to dinner more often and buying things I probably wouldn’t have bought otherwise.
By the end of sophomore year, I had accumulated around $2,000 in credit card debt.
I had a summer job, so I decided I’d just pay it off.
Problem solved, right?
Not exactly.
Normally, I saved the money I earned during the summer to pay for books, groceries, and other expenses during the upcoming school year.
Instead, I used much of that money to pay off my credit card.
I started junior year with almost no money.
So what happened when I needed books, groceries, and everything else?
Back onto the credit card they went.
I had paid off my debt without fixing the reason I needed the credit card in the first place.
The following summer, I took a different approach.
Instead of paying everything off again, I made the minimum payments and held onto more of my cash for senior year.
By the time I graduated, I was carrying roughly $4,500 in credit card debt.
After College, Things Got Worse
When I graduated from college, I had some pretty unrealistic expectations.
I figured I’d land a great job, make a lot of money, and probably be a company vice president within a few years.
Then reality showed up.
I couldn’t find a job.
I became depressed, and shopping became an escape. Buying clothes and electronics made me feel good for a little while.
The problem was that I was spending money I didn’t have.
Even worse, that feeling I got from buying something new started wearing off faster and faster.
For a while, I convinced myself I didn’t really have a debt problem.
Eventually, the balances became too large to ignore.
So naturally, I solved my credit card problem by…opening another credit card.
It offered a 0% balance transfer, and my plan sounded perfectly reasonable.
I’d move my existing balance to the new card, stop spending, save money on interest, and pay everything off.
Except I didn’t stop spending.
Now I had two credit cards with balances.
So I opened a third card and tried another balance transfer.
Same idea. Same problem.
Eventually, my credit card debt grew to more than $10,000.
Looking back, moving my balances around wasn’t fixing anything.
I was trying to solve the math without solving the behavior that created the debt.
The Jacket That Finally Woke Me Up
My turning point came in a clothing store.
I was trying on a jacket and was about to buy it when something clicked.
I remember thinking: Why am I buying another jacket? I already have three at home, and I don’t even wear one of them.
For whatever reason, that was the moment when I finally saw what I was doing.
I went home, pulled the clothes I’d bought out of my closet and bureau, and piled them onto my bed.
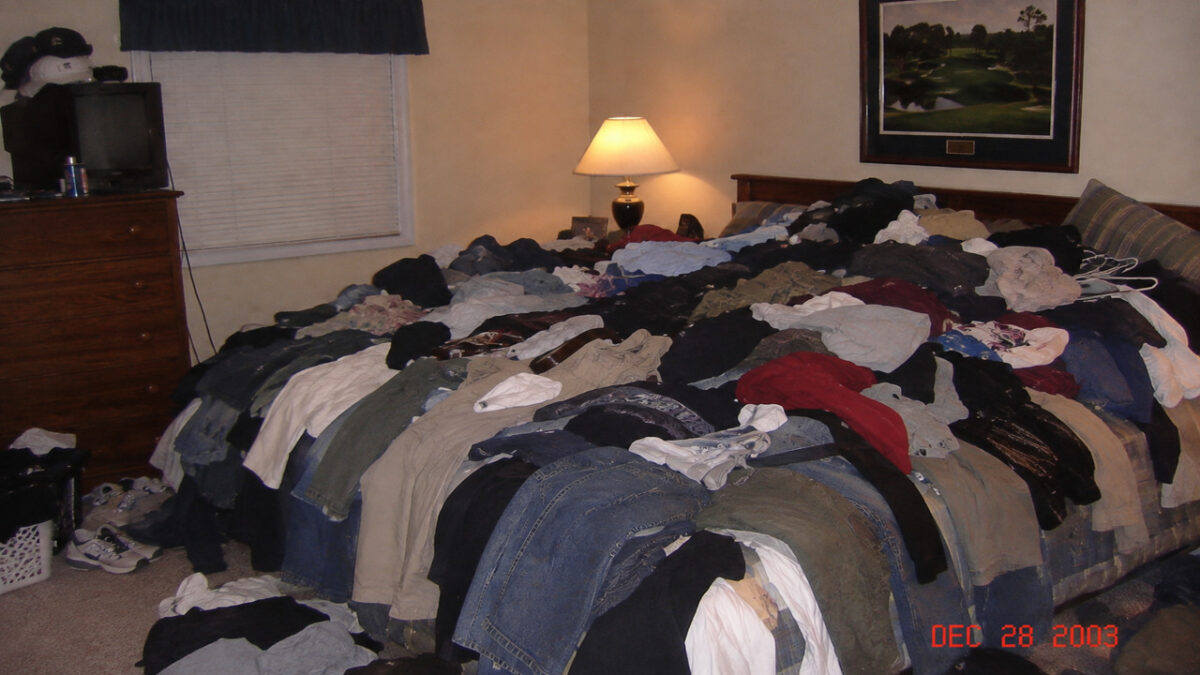
I took a picture of everything so I’d have a visual reminder of how much money I’d wasted.
I did the same thing with the electronics I’d bought.
But I also realized the spending itself wasn’t really my problem.
For me, shopping had become a way of dealing with low self-esteem and depression.
Until I dealt with those issues, moving debt from one credit card to another wasn’t going to accomplish much.
I started working on myself and began seeing a therapist.
Then I started working on the debt.
How I Finally Paid It Off
I got a part-time job and started putting the extra income toward my credit cards.
Eventually, I found a full-time job and was able to make much larger payments.
At first, I went too far.
I thought getting out of debt as quickly as possible meant every spare dollar should go toward my credit cards.
No eating out. No unnecessary purchases. No fun.
It worked financially.
Until it didn’t.
I started resenting my debt because it felt like I was working just to send money to a credit card company.
Eventually, I started spending again.
Fortunately, I caught myself before I undid all my progress.
Instead of abandoning my debt payoff plan, I changed it.
I gave myself a reasonable amount of money to enjoy life and continued putting the rest toward my debt.
That made the process slower on paper, but much more sustainable in real life.
And after a little more than a year, I had paid off more than $10,000 in credit card debt.
The Biggest Lesson I Learned
For years, I thought my problem was credit card debt.
It wasn’t.
The debt was the result of the problem.
My real problem was why I was spending money I didn’t have in the first place.
That’s why I think one of the most important steps in learning how to get out of debt happens before you send an extra dollar to your credit cards.
You need to understand how you got into debt.
Because you can have the perfect budget, use the debt snowball, transfer balances to a 0% card, and throw every extra dollar at your payments.
But if you never fix what caused the debt, there’s a good chance you’ll eventually end up right back where you started.
Before You Pay Off Debt: Figure Out Why You’re in Debt

Before you start throwing extra money at your debt, there’s an important question you need to answer: How did you get into debt in the first place?
The obvious answer might be, “I spent too much.”
But that’s often only part of the story.
In my case, overspending was the symptom.
The real problems were low self-esteem and depression.
Buying clothes and electronics gave me a temporary boost when I wasn’t feeling good about myself.
Until I understood that, I could move balances around and pay down my cards, but I hadn’t fixed what was causing me to spend.
Your reason could be completely different.
Maybe you never learned how to budget and simply spend more than you make.
Maybe your income dropped but your lifestyle didn’t.
Maybe an unexpected medical bill or home repair forced you to borrow.
Maybe you’re using credit cards to cover everyday expenses because your income isn’t enough.
Or maybe, like me, spending has become an emotional escape.
The reason matters because different causes require different solutions.
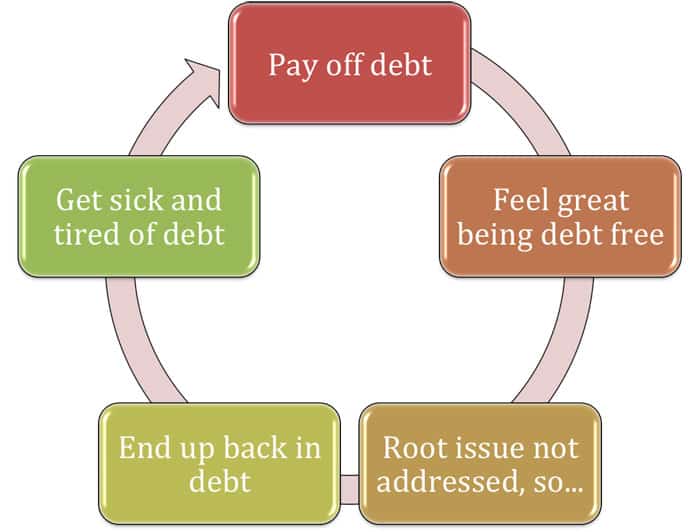
If you’re in debt because your expenses consistently exceed your income, you need to lower your expenses, increase your income, or both.
If an emergency wiped you out, you may need to build an emergency fund alongside your debt payoff plan so the next unexpected expense doesn’t go straight onto a credit card.
If impulse spending is the problem, you need to identify your spending triggers and put barriers between yourself and unnecessary purchases.
And if you’re using shopping to deal with something deeper, simply creating a stricter budget may not solve the underlying problem.
Ask Yourself These Questions
Before moving on, spend a few minutes looking back at how your debt accumulated.
Ask yourself:
- When did my debt start growing?
- What was happening in my life at the time?
- Was most of the debt caused by one event or hundreds of smaller purchases?
- Am I still spending more than I earn each month?
- Do I use credit cards when I’m stressed, bored, unhappy, or trying to keep up with other people?
- Could I cover a $500 or $1,000 unexpected expense today without going further into debt?
- Have I paid off debt before only to build the balances back up again?
Don’t use these questions to beat yourself up over past mistakes.
You’re trying to identify the problem so you can build a debt payoff plan that actually fixes it.
I learned this lesson the hard way.
I tried balance transfers and moved my debt from card to card because I thought the interest was the problem.
But I continued spending, so I eventually had balances on multiple cards and more than $10,000 in credit card debt.
I was treating the debt instead of what was creating the debt.
Once you understand why you’re in debt, you can start fixing both sides of the problem: paying off what you already owe while preventing new debt from replacing it.
Now it’s time to do exactly that.
How to Get Out of Debt: 10 Steps That Actually Work
Now that you understand why you’re in debt, it’s time to start getting rid of it.
The basic formula for paying off debt isn’t complicated: spend less than you earn and put the difference toward what you owe.
But knowing that and actually doing it month after month are two very different things.
The following steps will help you create a debt payoff plan you can stick with until your balances reach zero.
Step 1: Add Up All Your Debt
You can’t create a plan until you know exactly what you’re dealing with.
Make a list of every debt you owe and write down:
- Current balance
- Interest rate
- Minimum monthly payment
- Payment due date
Include credit cards, personal loans, student loans, medical debt, auto loans, and any other money you owe.
This part can be uncomfortable.
When I was in debt, I avoided looking at my balances because not knowing the exact number somehow felt better.
But the number doesn’t change just because you don’t look at it.
Once everything is in front of you, your debt stops being this vague financial problem hanging over your head.
It’s a number, and numbers can become a plan.
Add up all the balances to find your total debt. Don’t worry about how you’re going to pay it all off yet.
We’ll get to that.
Step 2: Stop Adding New Debt
This sounds obvious, but it’s one of the most important steps.
You can’t empty a bathtub while the faucet is still running.
If you’re paying $500 toward your credit cards every month but charging another $400, you’re technically making progress, but you’re going to be doing this for a very long time.
Look back at the reasons you identified in the previous section and start putting barriers between yourself and new debt.
That could mean removing saved credit cards from shopping websites, deleting shopping apps, unsubscribing from promotional emails, leaving your cards at home, or simply waiting 24 or 48 hours before making an unnecessary purchase.
You don’t necessarily have to close your credit cards or cut them into pieces.
The goal is simply to stop your balances from growing while you’re trying to pay them down.
This was the mistake I made with balance transfers.
I kept moving debt to new cards without stopping the spending that created it.
Instead of solving my problem, I eventually had balances on three cards.
Step 3: Build a Budget You Can Actually Live With
Next, figure out how much money you can realistically put toward your debt every month.
Start with your monthly take-home income and subtract your necessary expenses, including housing, utilities, groceries, transportation, insurance, and minimum debt payments.
Then look at everything else.
You will probably find expenses you can reduce or eliminate and redirect toward your debt.
But here’s where I want you to avoid the mistake I made: Don’t create a punishment budget.
When I first became serious about paying off my debt, I tried putting practically every available dollar toward it.
I left myself almost nothing to enjoy life.
Eventually, I became frustrated, started resenting my debt, and began spending again.
Your budget needs to be aggressive enough to make progress but realistic enough that you can follow it for months or even years.
If leaving yourself $50 or $100 of fun money each month keeps you from blowing $500 after three months of deprivation, that’s money well spent.
Step 4: Build a Small Emergency Fund
It might seem strange to save money when you’re trying to pay off debt, especially if your credit cards are charging high interest rates.
But without any savings, the next unexpected expense can send you straight back into debt.
Your car needs a $700 repair.
The water heater dies.
You have an unexpected medical bill.
Without cash available, the credit card comes back out.
You don’t necessarily need a fully funded emergency fund before aggressively paying down high-interest debt.
Start with a small emergency cushion that can handle the kinds of unexpected expenses that normally end up on your credit card.
For some people, that might be $1,000.
For others, it could be one month’s worth of essential expenses.
Once your high-interest debt is gone, you can turn your attention toward building a larger emergency fund.
Step 5: Choose a Debt Payoff Strategy
Now decide which debt you’re going to attack first.
Two of the most popular approaches are the debt snowball and debt avalanche.
With the debt snowball, you pay off your smallest balance first while making minimum payments on everything else.
Once that debt disappears, you roll its payment into the next-smallest debt.
With the debt avalanche, you attack the debt with the highest interest rate first.
Once it’s paid off, you move to the debt with the next-highest rate.
The avalanche generally saves more money on interest.
The snowball gives you faster psychological wins.
Which is better?
The one you’ll actually stick with.
We’ll compare both methods in detail shortly.
Step 6: Pay More Than the Minimum
Minimum payments are designed to keep your account current.
They aren’t designed to help you get out of debt quickly.
Continue making at least the minimum payment on every debt, but put all the extra money you’ve identified in your budget toward your target debt.
For example, suppose your minimum payment is $150 and you’ve found another $300 in your budget.
Don’t make a $150 payment and let the $300 disappear into your checking account.
Make a $450 payment.
When that debt is gone, take the entire $450 and add it to the minimum payment you were already making on the next debt.
That’s when your payoff plan starts gaining momentum.
Step 7: Look for Ways to Lower Your Interest Rates
Every dollar you don’t pay in interest is another dollar that can go toward eliminating your balance.
Call your credit card companies and ask whether they can lower your interest rate.
You may be surprised by what happens simply by asking, particularly if you’ve consistently made your payments on time.
Depending on your credit and financial situation, other options could include a 0% balance transfer card or debt consolidation loan.
But be careful.
Lowering your interest rate only helps if you stop accumulating new debt.
I learned that personally.
A zero percent balance transfer looked like the perfect solution to my problem, but because I hadn’t fixed my spending, I eventually accumulated debt on the new card too.
Use lower interest rates as a tool for paying off debt, not as an excuse to create room for more spending.
Step 8: Find Extra Money to Put Toward Your Debt
Once you’ve established your regular monthly payment, look for opportunities to make additional payments.
You don’t have to completely overhaul your life.
Look for money that’s already passing through your hands:
- Tax refunds
- Work bonuses
- Cash gifts
- Rebates
- Cash back
- Things you can sell
- Money left over from your grocery or entertainment budget
Instead of letting these small windfalls disappear into everyday spending, send some or all of them toward your target debt.
Even an extra $50 here and $100 there adds up.
And remember: extra payments don’t have to be permanent to matter.
If you can temporarily cut an expense for six months and redirect $100 a month toward your credit card, that’s another $600 you’ve knocked off the balance before even considering the interest you avoided.
Step 9: Increase Your Income
There are only so many expenses you can cut.
Your income, on the other hand, has much more room to grow.
When I was paying off my debt, I got a part-time job and put that additional income toward my credit cards.
Once I found a full-time job, I was able to put my repayment plan into overdrive.
You could pick up overtime, ask for additional shifts, freelance, sell a service, take on a temporary second job, or start a side hustle.
You don’t have to do it forever.
If working an extra five or ten hours a week for a year knocks several years off your debt payoff timeline, the temporary sacrifice could be worth it.
Just make sure the additional income actually goes toward the debt.
It’s surprisingly easy for your spending to increase as soon as your income does.
Step 10: Track Your Progress and Celebrate Milestones
Getting out of debt can take a long time, and staring at one giant number can make it feel like you’re getting nowhere.
I experienced this when I was paying off my $10,000+ balance.
Making a $150 payment didn’t feel like much progress when I compared it with the entire amount I owed.
So instead of focusing on $10,000, I focused on paying off the next $1,000.
Suddenly, I had a goal that felt achievable.
Do the same thing with your debt.
If you owe $30,000, don’t make $30,000 the only victory that counts.
Celebrate when you get below $25,000.
Celebrate your first credit card reaching $0.
Celebrate paying off $5,000.
Celebrate when your monthly interest charge drops.
Celebrate reaching the halfway point.
You don’t need to spend a bunch of money celebrating, that would defeat the purpose.
But acknowledging your progress makes a long debt payoff journey feel like a series of smaller wins instead of one enormous sacrifice.
Every payment is buying back a little more of your future income.
Want a Step-by-Step Plan to Get Out of Debt?
Knowing what to do is one thing.
Actually sticking with a debt payoff plan month after month is where things get harder.
That’s why I created the Debt-Free Blueprint.
It walks you through the process step by step, with 27 lessons, a 100+ page workbook, an automated debt tracker, budgeting tools, and resources designed to help you build a payoff plan you can actually stick with.
Instead of piecing together advice from dozens of articles, you’ll have the entire process organized in one place.
Reading about debt is a great first step, but lasting progress comes from having a clear plan. Debt Free Blueprint gives you a step-by-step system, debt payoff tracker, workbook, budgeting tools, and practical strategies to help you eliminate debt faster and stay motivated along the way.
Take the guesswork out of becoming debt-free.
Debt Snowball vs. Debt Avalanche: Which Should You Use?
Once you have extra money to put toward your debt, you need to decide which debt to pay off first.
Two of the most popular strategies are the debt snowball and debt avalanche.
Both work the same basic way: you make the minimum payment on every debt, put all your extra money toward one debt, and then roll that payment into the next debt once the first one is gone.
The difference is which debt you attack first.
Debt Snowball
With the debt snowball method, you organize your debts from the smallest balance to the largest balance, regardless of the interest rate.
You put all your extra money toward the smallest debt while continuing to make minimum payments on everything else.
Once the smallest debt is paid off, you move that entire payment to the next-smallest debt.
For example, if you have:
| Debt | Balance | Interest Rate |
|---|---|---|
| Credit Card #1 | $1,500 | 18% |
| Personal Loan | $4,000 | 12% |
| Credit Card #2 | $7,500 | 24% |
With the snowball method, you’d attack the $1,500 credit card first, even though another card has a higher interest rate.
The advantage is motivation.
You can eliminate smaller balances relatively quickly, giving you an early win and one less monthly payment to worry about.
Debt Avalanche
The debt avalanche method prioritizes the highest interest rate instead of the smallest balance.
Using the same example, you’d attack the $7,500 credit card at 24% first, followed by the 18% credit card and then the 12% personal loan.
Mathematically, the avalanche usually comes out ahead because you’re eliminating your most expensive debt first.
That means you’ll generally pay less total interest and, assuming the same payment amount, get out of debt sooner.
The downside is that your first payoff can take longer, especially if your highest-interest debt also has a large balance.
Which Debt Payoff Method Is Better?
Here’s the easiest way to think about it:
- Debt snowball: Prioritizes quick wins and motivation.
- Debt avalanche: Prioritizes saving money on interest.
There’s no rule saying you have to use one or the other.
If seeing accounts disappear keeps you motivated, the snowball may be worth paying a little more interest.
If you’re motivated by knowing you’re minimizing the cost of your debt, the avalanche may make more sense.
What’s more important is that you pick a method and consistently put extra money toward your target debt instead of bouncing between strategies.
I have a complete breakdown of the debt snowball vs. debt avalanche, including examples and the pros and cons of each, if you want help deciding which approach makes the most sense for you.
How to Get Out of Debt When You Have No Money
One of the most frustrating pieces of debt advice is being told to “just pay extra.”
That’s great advice if you have an extra $500 sitting around every month.
But what if you don’t?
If your paycheck is already going toward housing, groceries, utilities, transportation, and minimum debt payments, getting out of debt requires a slightly different approach.
Your first goal isn’t necessarily to make huge extra payments.
It’s to create some breathing room in your monthly budget so you eventually can.
Start With the Expenses Keeping Your Life Running
When money is extremely tight, don’t skip groceries or fall behind on your electric bill just so you can send extra money to a credit card.
Prioritize necessities such as housing, food, utilities, transportation, insurance, and other essential expenses.
Then make at least the minimum payments on your debts if you’re able.
After that, look for expenses you can temporarily reduce or eliminate.
The key word is temporarily.
You don’t have to swear off restaurants, vacations, streaming services, or anything fun for the rest of your life.
You’re trying to create some extra cash flow while you get your finances under control.
Even finding $100 a month gives you $1,200 a year that can eventually go toward your debt.
Look for Bigger Wins Before Cutting Every Little Expense
When you’re already struggling financially, obsessing over every $3 purchase probably isn’t going to change your situation.
Look at your largest expenses first.
Could you shop around for cheaper car insurance?
Switch your cell phone plan?
Cancel subscriptions you’re barely using?
Negotiate your internet bill?
Spend less on groceries without dramatically changing what you eat?
Temporarily reduce how often you eat out?
One $75 monthly expense you eliminate is worth the same as finding fifteen different ways to save $5.
You can certainly do both, but start where you’ll get the biggest return for your effort.
Call Your Creditors Before You Fall Behind
If you’re struggling to make your minimum payments, don’t wait until you’ve missed several of them to ask for help.
Contact your creditors and explain your situation.
Depending on the lender and your circumstances, there may be hardship options available that temporarily reduce your payment, lower your interest rate, waive certain fees, or otherwise make your payments more manageable.
You won’t know what’s available unless you ask.
And if you’re already behind, don’t avoid the calls because you’re embarrassed.
Ignoring the debt won’t make the balance disappear.
I spent plenty of time avoiding bills when I was in debt.
All it accomplished was giving me something to worry about while I wasn’t looking at them.
Find Money Outside Your Regular Paycheck
If there’s truly nothing left to cut from your budget, then cutting expenses isn’t going to solve the problem.
You need more income.
That doesn’t necessarily mean starting some elaborate side business.
Think short term.
Work overtime. Pick up an extra shift. Get a part-time job. Sell things around your house you no longer use. Do freelance work. Take on seasonal work.
When I was getting out of debt, getting a part-time job was one of the things that finally allowed me to start making meaningful progress.
Even an additional $200 or $300 a month can completely change a debt payoff plan when you previously had $0 left over.
The important part is deciding before you earn the money how much of it will go toward your debt.
Otherwise, it’s easy for your lifestyle to expand along with your income.
Don’t Ignore a Small Emergency Fund
When you barely have enough money to pay your bills, saving money instead of paying debt can feel backward.
But having absolutely nothing in savings makes it incredibly easy to fall deeper into debt.
You finally pay $500 off your credit card.
Then your car needs a $500 repair.
The balance goes right back up.
Even a small emergency fund can help break that cycle. You can start small and build it gradually while continuing to make your required debt payments.
What If You Can’t Afford Your Minimum Payments?
This is where the situation changes.
If you’ve cut what you reasonably can, increased income where possible, and still can’t afford the minimum payments on your debts, you may need more than a DIY debt payoff strategy.
Start by contacting your creditors to ask about hardship options.
You can also speak with a reputable nonprofit credit counseling agency.
A credit counselor can review your income, expenses, and debts and help you understand your options.
Depending on your situation, a debt management plan may also be worth considering.
We’ll cover credit counseling and other professional options later in this guide.
Most importantly, don’t fall for anyone promising to make your debt disappear quickly or easily.
The more desperate you feel, the more attractive a too-good-to-be-true solution can sound.
Your First Goal Is to Create a Gap
If you have no money available for extra debt payments today, don’t look at someone paying an extra $1,000 a month and assume you’re doomed.
Your first milestone can be much smaller.
Maybe you find $25.
Then $50.
Then $100.
That gap between what you earn and what you spend is what eventually gives you the money to attack your debt.
You don’t need to find hundreds of dollars overnight.
You need to create the first dollar of breathing room, and then keep widening the gap.
Ways to Lower the Cost of Your Debt
Paying more toward your debt is one way to get rid of it faster.
But there’s another side of the equation that’s easy to overlook: make the debt itself less expensive.
If you’re carrying high-interest debt, a significant portion of every payment may be going toward interest instead of reducing what you actually owe.
For example, a $10,000 credit card balance at 25% APR can generate roughly $2,500 in interest over a year if the balance stayed around $10,000.
Lowering that interest rate means more of each payment can attack the principal.
There are several ways you may be able to do that.
Ask for a Lower Interest Rate
Start with the easiest option: call your credit card company and ask.
If you’ve been a customer for a while and have a history of making payments on time, the issuer may be willing to reduce your APR.
There’s no guarantee they’ll say yes, but the phone call costs you nothing.
You can simply explain that you’re working on paying down your balance and ask whether there are any lower-rate options available for your account.
Even a few percentage points can make a difference when you’re carrying a large balance.
Consider a 0% Balance Transfer
A balance transfer credit card allows you to move debt from one or more credit cards to another card, potentially with a 0% introductory APR for a limited period.
That can give you a window where your payments go toward reducing the balance instead of being eaten up by interest.
But pay attention to the details.
Balance transfers commonly charge a fee, and the 0% rate doesn’t last forever.
You’ll want to know when the promotional period ends and what interest rate applies afterward.
More importantly, don’t make the mistake I did.
I transferred my debt to a 0% card but continued spending.
Eventually, I had a balance on the old card and the new one. Then I opened another card and repeated the process.
A balance transfer can be useful if it is part of a debt payoff plan.
It’s not useful if you’re simply moving debt around while continuing to create more of it.
Look Into a Debt Consolidation Loan
Another option is a debt consolidation loan.
With debt consolidation, you take out a new loan and use the money to pay off multiple existing debts.
Instead of making payments to several creditors, you make one payment on the consolidation loan.
This can make your finances easier to manage, but convenience isn’t the main reason to consider consolidation.
What really matters is the math.
Suppose you have several credit cards charging 20% to 30% interest and qualify for a personal loan at a significantly lower rate.
Consolidating those balances could reduce the amount of interest you pay and potentially help you get out of debt faster.
But don’t assume consolidation automatically saves money.
Compare the new loan’s:
- Interest rate
- Fees
- Monthly payment
- Repayment period
- Total amount you’ll repay
A lower monthly payment can look attractive simply because the debt is being stretched over a longer period.
You could end up staying in debt longer or paying more overall.
Negotiate With Your Creditors
If you’re struggling financially, contact your creditors and ask what options they offer.
Depending on the creditor and your circumstances, you may be able to get a temporary interest-rate reduction, payment arrangement, hardship program, or certain fees waived.
Again, the key is to contact them.
Don’t assume there’s nothing they can do.
And whenever you agree to a new arrangement, make sure you understand the terms before accepting it.
Refinancing Can Make Sense for Some Debts
Refinancing replaces an existing loan with a new one, ideally with better terms.
This can potentially make sense for certain auto loans, private student loans, personal loans, or other debts if your credit or financial situation has improved since you originally borrowed the money.
But don’t refinance simply because you can get a smaller monthly payment.
A $400 payment can look much better than a $600 payment until you realize you’ve added several years to the loan.
Look at the total cost, not just the monthly payment.
Also be especially careful when refinancing federal student loans with a private lender.
Doing so can mean permanently giving up federal benefits and protections that may be valuable to you.
Debt Consolidation and Debt Settlement Aren’t the Same Thing
These two terms are sometimes used interchangeably, but they’re very different.
Debt consolidation generally means combining multiple debts into a new loan or repayment arrangement. You’re still planning to repay what you owe.
Debt settlement involves trying to get a creditor to accept less than the full amount owed.
Settlement can have significant consequences, including damage to your credit, fees, collection activity, and potentially taxes on forgiven debt depending on your circumstances.
Be particularly cautious of debt settlement companies that tell you to stop paying creditors or promise they can easily make a large portion of your debt disappear.
If you’re unable to keep up with your debts, I’d look at your full range of options, including nonprofit credit counseling, rather than jumping at the first company promising a quick fix.
Remember What You’re Actually Trying to Accomplish
Whether you’re considering a balance transfer, consolidation loan, refinance, or lower interest rate, ask yourself one question: will this help me pay off my debt for less money, faster, or both?
Don’t move debt around just to make the monthly payment look better.
Run the numbers.
And most importantly, make sure you’ve addressed the spending or financial problem that created the debt in the first place.
Otherwise, you could end up with exactly what I did: a better interest rate and even more debt.
When You Need Help Getting Out of Debt
There comes a point where cutting expenses, working more, and following a debt payoff plan may not be enough.
Maybe you can barely afford your minimum payments.
Maybe you’ve already fallen behind.
Or maybe you’re juggling so many debts that you don’t know which direction to go.
If that’s where you are, getting professional help isn’t the same as giving up control of your finances.
A good counselor should help you understand your options and create a realistic path forward.
Start With Nonprofit Credit Counseling
A good place to start is a nonprofit credit counseling agency.
A credit counselor can review your income, expenses, and debts with you and help determine why you’re struggling to keep up.
Depending on your situation, they may help you:
- Create a realistic budget
- Develop a debt repayment plan
- Understand the different options available to you
- Work with creditors
- Find ways to reduce interest rates or certain fees
- Decide whether a debt management plan makes sense
You don’t have to wait until you’re months behind on your bills, either.
If you can see that your current situation isn’t sustainable, getting help earlier may give you more options.
What Is a Debt Management Plan?
If you have significant unsecured debt, a credit counseling agency may recommend a debt management plan, or DMP.
With a debt management plan, you generally make one monthly payment to the credit counseling agency, which then distributes the money to participating creditors.
Depending on agreements with your creditors, you may receive reduced interest rates or waived fees, which can make the debt easier to repay.
A debt management plan is not a loan, and it doesn’t erase your debt.
You’re still repaying what you owe, but you’re doing it through a structured repayment program.
There may also be fees involved, so make sure you understand the costs and terms before enrolling.
How to Find a Reputable Credit Counselor
Unfortunately, being in financial trouble can make you a target for companies promising an easy way out.
That’s why you need to do some homework before working with anyone.
One place to begin your search is the National Foundation for Credit Counseling (NFCC), which can connect you with nonprofit member agencies.
When comparing credit counseling organizations, look for one that clearly explains its services and fees, uses trained or certified counselors, takes the time to review your entire financial situation, and doesn’t pressure you into immediately signing up for a particular program.
Be especially cautious if someone promises to eliminate your debt, guarantees a specific result before reviewing your finances, or demands a large payment before explaining what they’re actually going to do.
Credit Counseling vs. Debt Settlement
It’s also important not to confuse credit counseling with debt settlement.
Credit counseling generally focuses on helping you manage your finances and repay your debts.
A debt management plan may be part of that process.
Debt settlement takes a different approach.
A settlement company typically attempts to negotiate with creditors so they’ll accept less than the full amount you owe.
That can come with significant risks and consequences, which is why I wouldn’t treat debt settlement as interchangeable with credit counseling just because both services advertise help with debt.
When Should You Consider Getting Help?
You don’t need professional help simply because you have debt.
If you’re making your payments and have enough money left each month to consistently reduce your balances, you may be perfectly capable of following a DIY debt payoff plan.
But I’d consider talking with a nonprofit credit counselor if:
- You regularly can’t afford your minimum payments.
- You’re using one credit card or loan to pay another.
- You’re falling further behind each month.
- Most of your payment seems to disappear into interest.
- Collection calls have started.
- You don’t see a realistic way to repay your debts with your current income.
- You’ve tried repeatedly to create a payoff plan but can’t make the numbers work.
The important thing is not to wait for the situation to become a crisis before asking what your options are.
Sometimes the solution is simply a better budget and repayment strategy.
Sometimes you may benefit from a structured debt management plan.
What About Bankruptcy?
Bankruptcy is a more serious option for dealing with debt, but it shouldn’t automatically be viewed as either a failure or an easy escape.
For some people, it simply isn’t necessary.
A budget, debt payoff plan, lower interest rates, or credit counseling may be enough to get their finances back under control.
For others, the numbers may no longer work.
If you have overwhelming debt that you realistically can’t repay, are facing collection actions, or can’t make meaningful progress despite cutting expenses and exploring other options, bankruptcy may be worth discussing with a qualified bankruptcy attorney.
Bankruptcy is a federal legal process that can discharge certain debts or establish a court-supervised repayment plan.
Exactly what happens depends on the type of bankruptcy, your income, assets, debts, and other circumstances.
Chapter 7 vs. Chapter 13 Bankruptcy
For individuals, the two types you’ll hear about most often are Chapter 7 and Chapter 13.
Chapter 7 bankruptcy is commonly referred to as liquidation bankruptcy.
Certain nonexempt property can potentially be sold by a bankruptcy trustee to repay creditors, although the U.S. Courts notes that many Chapter 7 cases are “no-asset” cases.
Eligibility can also depend on a means test for people with primarily consumer debts.
Chapter 7 can discharge many types of unsecured debt, including qualifying credit card and medical debt.
Chapter 13 bankruptcy works differently.
Instead of liquidating nonexempt assets, individuals with regular income generally follow a court-approved repayment plan lasting three to five years.
Chapter 13 can also allow someone to keep certain property while catching up on debts through the repayment plan.
Here’s the basic difference:
| Details | Chapter 7 | Chapter 13 |
|---|---|---|
| Basic Approach | Discharges qualifying debts, with nonexempt assets potentially subject to liquidation | Repayment plan |
| Typical Timeline | Often much shorter | Usually 3–5 years |
| Income | Subject to eligibility requirements, including a means test in applicable consumer cases | Designed for people with regular income |
| Property | Nonexempt property may potentially be sold | Generally allows you to keep property while following the repayment plan |
The rules are much more complicated than this table can show, so don’t choose between Chapter 7 and Chapter 13 based solely on a summary you read online.
Bankruptcy Doesn’t Eliminate Every Debt
Another common misconception is that filing bankruptcy automatically wipes out everything you owe.
It doesn’t.
Which debts can be discharged depends partly on the bankruptcy chapter and circumstances.
Certain debts generally aren’t dischargeable, including child support and alimony, certain taxes, and most government-funded or guaranteed student loans.
There are other exceptions as well.
That’s one reason I’d avoid making assumptions about what bankruptcy would or wouldn’t eliminate in your particular situation.
Don’t Rule It Out or Rush Into It
Bankruptcy can have significant financial and legal consequences, but carrying unmanageable debt for years can have serious consequences too.
So I wouldn’t look at bankruptcy as something you should automatically avoid at all costs.
I’d look at it as one of the options available when the debt has become too large for a realistic repayment plan.
If you think you’re at that point, talk with a qualified bankruptcy attorney who can look at your actual financial situation.
You can also speak with a nonprofit credit counselor about alternatives before deciding what makes sense.
The goal isn’t to choose the option that sounds the least scary.
It’s to understand all of your options and make an informed decision about the best way forward.
How Long Does It Take to Get Out of Debt?
Related
 Teachers' Union of Ireland
 Buckhead Family Law Blog
 Best Wallet Hacks
 Ciente Blog
 Cup of Jo
 Steve Biz Blog
More from Money Smart Guides